Renters Insurance in Summerville, SC
Protect Your Stuff. Protect Your Peace of Mind.
Your landlord protects the building. But what about everything inside that's yours? From your first apartment to your next rental home, The Farnsworth Family Agency helps renters in Summerville and across South Carolina find coverage that fits their needs. We can also review your auto insurance for potential bundling opportunities.
Get My Renters Insurance Quote
A quick form. No obligation. Our team will follow up to talk through your options.
What Renters Insurance Can Protect
A renters policy is built around your belongings and your responsibility as a tenant — not the building itself.
Personal property
Covers your furniture, clothing, electronics, kitchen items, and other belongings inside the rental, up to the limits and for the causes of loss the policy actually covers.
Personal liability
Helps respond if you're legally responsible for someone else's injury or for damage you cause to someone else's property — including claims that arise away from home.
Loss of use
If a covered loss makes your rental unlivable, this can help with temporary housing and added living costs while it's repaired. Also called additional living expenses.
Optional higher-value items
Jewelry, watches, silverware, furs, firearms, and cash are typically subject to special sub-limits. Higher-value items usually need a scheduled endorsement or separate coverage.
Your landlord's policy is not your policy
Your landlord insures the building — the structure, and usually the property they own. Their policy doesn't cover your furniture, clothes, or electronics, and it generally doesn't cover your liability as a tenant. Your renters policy is the one that responds to your belongings and your responsibility.
Renters coverage is not flood insurance, and it generally doesn't insure the building itself. Those are separate conversations.
Why Renters Insurance Matters
These are the situations renters in Summerville actually call us about.
Moving into a first apartment
A new lease usually comes with a list of things you own and a list of things you'd have to replace. Renters coverage is often the cheapest way to close that gap before you unpack.
Renting a house or townhome
Renting a whole house doesn't change who insures what. Your landlord still insures the structure; your belongings, your liability, and your temporary housing after a covered loss are still yours to handle.
Meeting a lease requirement
Many landlords and property managers require tenants to carry renters coverage and to show proof. A policy also satisfies lease language that makes you responsible for damage you cause.
Replacing belongings after a covered loss
Fire, theft, and certain water damage can wipe out years of accumulated possessions at once. Whether you're repaid on a replacement cost or actual cash value basis changes what you actually receive.
Protecting yourself from liability claims
A guest injured in your rental, or damage you accidentally cause to a neighboring unit, can turn into a claim against you. Liability coverage is the part of the policy most renters overlook.
What a policy pays depends on its terms, exclusions, limits, and deductible. Two renters with the same belongings can end up with very different outcomes, which is why it's worth reading the policy rather than the brochure.
Renting? Let's Look at Your Auto Insurance, Too.
Many carriers offer a multi-policy discount, or other benefits, when an eligible renters policy and an auto policy are placed together. Whether that applies to you depends on the carrier, the policies, and your own eligibility — not every combination qualifies, and the amount varies.
So we treat it as an optional review. You can ask us to look at both while we're talking about renters coverage, or just handle renters now and come back to auto later. Auto coverage is never required to get a renters policy from us.
- We look at your current auto coverage and limits with you.
- We check whether any multi-policy discount applies to your situation, under the carrier's own rules.
- You decide what, if anything, to change. Nothing is switched without your say-so.
What we won't tell you
We won't promise you a discount before we've checked whether you qualify, and we won't promise the lowest rate in the market. Discounts are set by each carrier, and eligibility rules vary by company and by policy.
If bundling doesn't help in your case, we'll say so. Sometimes a separate policy is the better answer, and sometimes the carrier that fits you best for renters isn't the one that fits you best for auto.
Reading your current declarations pages before we talk usually makes the review more useful.
Renters Insurance, Explained
The six things renters ask us about most, in plain language.
Replacement cost vs. actual cash value
Replacement cost coverage pays to replace damaged belongings with new items of similar kind and quality, up to your policy limits. Actual cash value pays the value of the item at the time of loss — what it was worth used, which is usually less.
The difference matters most on older electronics, furniture, and clothing. A five-year-old laptop reimbursed at replacement cost and the same laptop reimbursed at actual cash value are very different numbers, and the settlement method is stated in the policy you buy.
How deductibles work
A deductible is the amount you're responsible for before the policy responds to a covered loss. A $1,000 deductible on a $6,000 covered loss typically means the policy handles the remaining $5,000, subject to limits and the policy's terms.
A higher deductible usually lowers the premium, but it also raises the amount you'd have to come up with at the worst possible moment. Choosing a deductible you could actually pay is part of the decision.
How to estimate the value of your belongings
Walk through your rental one room at a time and note what it would cost to replace each item today, not what you paid for it. Photos and a quick list are enough to start, and they double as documentation if you ever file a claim.
Don't skip the unglamorous things. Kitchenware, bedding, towels, cleaning supplies, tools, and the contents of a closet add up faster than most people expect.
Whether roommates are covered
Usually not automatically. A renters policy typically covers the named insured and resident relatives, not an unrelated roommate and not their belongings.
If you share a rental, each person who needs coverage usually needs to be addressed on the policy. Some carriers will insure roommates together and some won't, so this is worth raising before you sign a lease together.
Why renters may need separate flood insurance
A standard renters policy generally does not cover flood — rising water is typically excluded. That means a storm surge, an overflowing creek, or water that enters from outside can leave your belongings uncovered.
Flood coverage for your personal property is available separately, through the National Flood Insurance Program or a private flood carrier. Flood policies commonly have a waiting period before coverage takes effect, so timing matters if a storm is already in the forecast.
Why your landlord's insurance doesn't cover your belongings
Your landlord's policy is there to protect the building they own and their own financial interest in it. It is not written to protect your property, and it doesn't respond to your liability as a tenant.
This is the part that surprises people most after a fire or a burglary: the building gets repaired while the tenant discovers that none of their belongings were ever insured.
General information only. Coverage, limits, and exclusions are set by the policy actually issued. For consumer guidance on renters coverage in South Carolina, see the South Carolina Department of Insurance.
A Local Summerville Agency
The Farnsworth Family Agency is a locally owned, family-operated insurance agency based in Summerville, South Carolina. We help renters in Summerville, Charleston, Berkeley and Dorchester counties, the Lowcountry, and customers throughout South Carolina review their personal coverage.
Rental coverage is one of those things that's easy to buy badly online and hard to ask questions about afterward. Our office is at 421 Old Trolley Road, so you can stop in, call, or sit down with our team in person.
Meet the team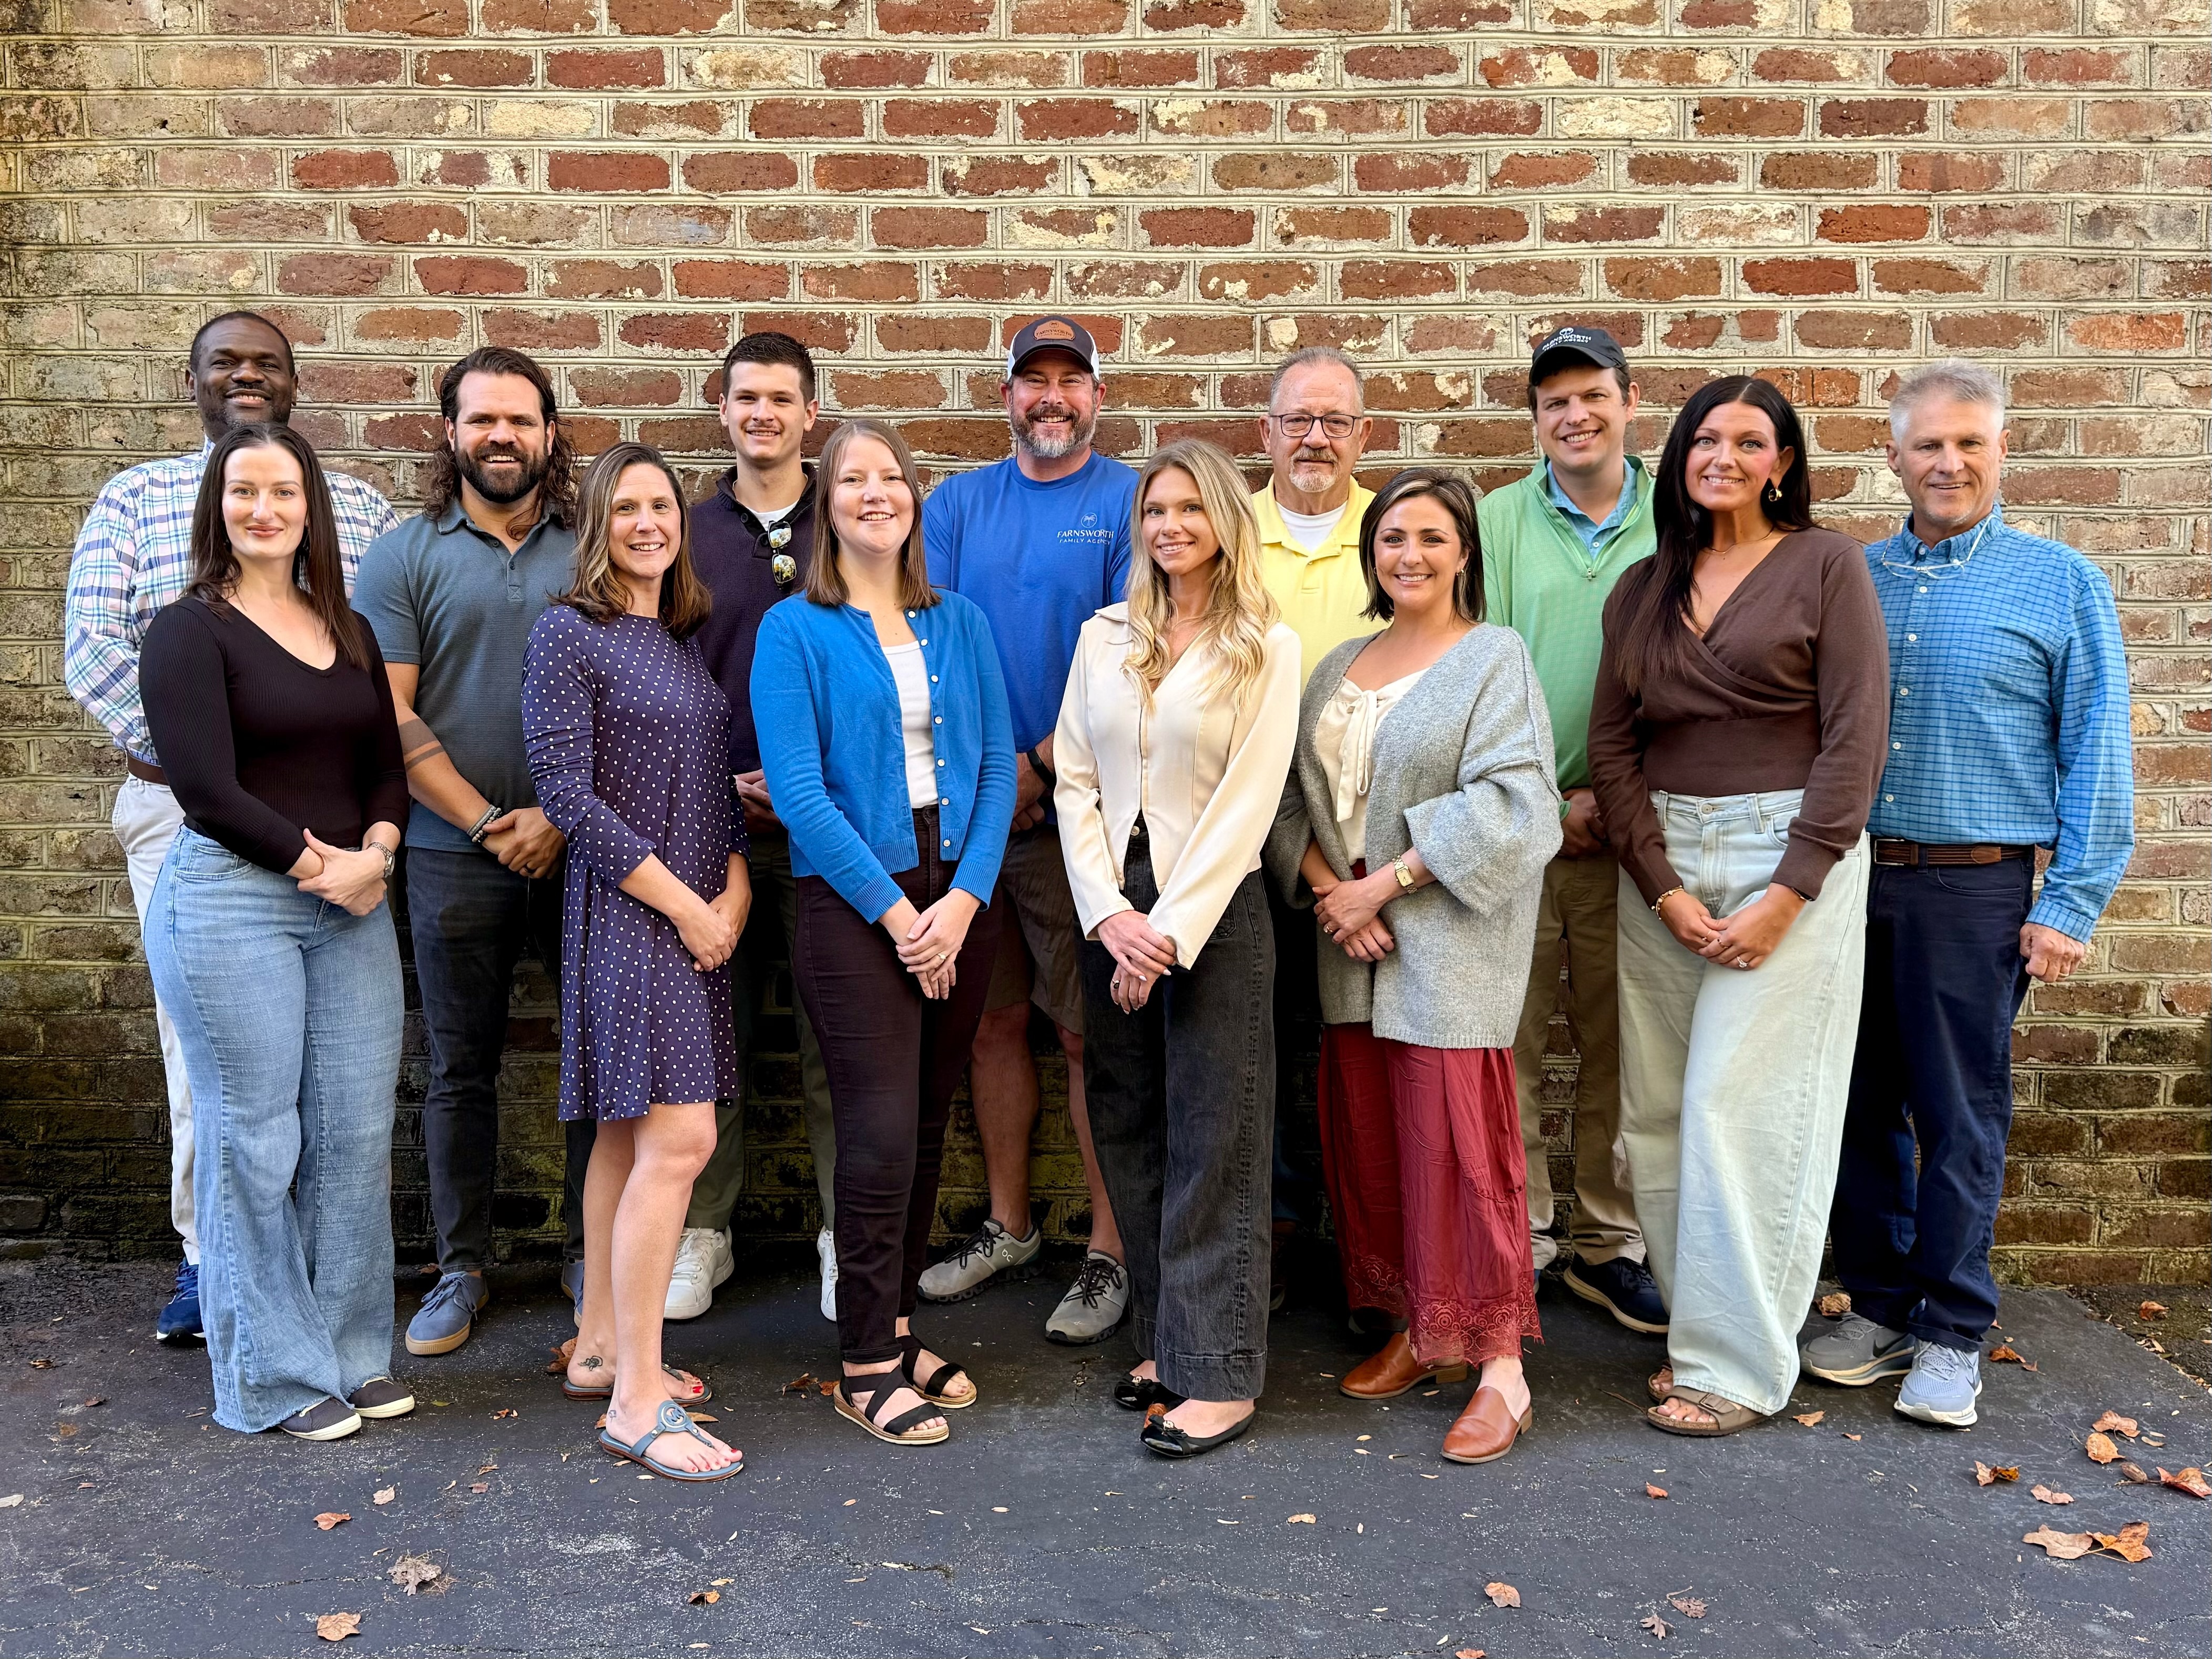
Locally owned and family-operated
The Farnsworth Family Agency is a family-owned insurance agency, not a call center. You work with the same team year after year.
An actual conversation
We'll ask what you own, what your lease requires, and what you'd want to happen after a loss — then explain what a policy does and doesn't do.
Renters Insurance Questions
Straight answers to what renters in Summerville ask us most.
Is renters insurance required in South Carolina?
South Carolina does not require renters insurance by law. Auto liability coverage is required for drivers, but there's no state mandate that a tenant carry renters coverage. That said, many landlords and property managers require it in the lease, and a lender or property manager may ask for proof before you move in.
Can my landlord require renters insurance?
Yes. A landlord can make renters insurance a condition of the lease, and many do. They typically ask for proof of coverage at move-in and at renewal, and the lease may set a minimum amount of liability coverage. If your lease requires it, the requirement is a contract term between you and your landlord — not a state law.
How much does renters insurance cost in Summerville?
We can't quote a number without looking at your situation. Premiums depend on the amount of personal property coverage you choose, your deductible, your liability limits, the location and type of rental, the carrier, and any optional endorsements. Renters policies are generally less expensive than homeowners policies, but the only accurate figure is one based on your actual coverage choices.
Does renters insurance cover theft?
Theft is commonly a covered cause of loss on a renters policy, subject to your deductible, your policy limits, and any special sub-limits for categories like jewelry or cash. Coverage generally follows your belongings when you're away from the rental, still within the limits and sub-limits your policy sets. Check the specific policy language — and note that a theft claim typically also requires a police report.
Does renters insurance cover flooding?
Generally no. Flood — rising water from outside, storm surge, or an overflowing body of water — is typically excluded from a standard renters policy. Flood coverage for your personal property is purchased separately, through the National Flood Insurance Program or a private flood carrier. Those policies commonly have a waiting period before coverage begins, so it's worth arranging before a storm is forecast.
Can I bundle renters and auto insurance?
Sometimes. Many carriers offer a multi-policy discount when an eligible renters policy and an auto policy are written together, and some offer other benefits for doing so. Eligibility, the discount amount, and the rules vary by carrier and by policy, and not every combination qualifies. We'll check what's available in your case — but we won't promise a discount before we've confirmed you qualify, and auto coverage is never required to buy renters insurance.
Does renters insurance cover roommates?
Usually not automatically. A renters policy typically covers the named insured and resident relatives, not an unrelated roommate or their belongings. If you share a rental, each person who needs coverage generally needs to be addressed on the policy. Some carriers will write roommates together and some won't, so it's worth sorting out before you sign a lease.
Do I need renters insurance when renting a house?
The type of rental doesn't change who insures what. When you rent a house or townhome, the owner's policy covers the structure; your belongings, your liability as a tenant, and your temporary housing after a covered loss are still yours to protect. Whether you're required to carry it depends on your lease, not on whether the rental is an apartment or a house.
What does personal liability coverage do?
Personal liability coverage responds when you're legally responsible for someone else's bodily injury or for damage to someone else's property. That can include a guest injured in your rental, or damage you cause to a neighboring unit. It typically also covers related legal costs, up to the policy limit, and it usually follows you away from home. The limit you choose is the most you'd have available for those claims.
How quickly can I request a renters insurance quote?
The form on this page takes a couple of minutes. A member of our team follows up during business hours to go over your options — we won't promise a specific turnaround, and nothing is bound until you've reviewed the coverage and said yes. If your lease requires proof of coverage by a certain date, tell us that date and we'll work from it.
Other coverage our Summerville team handles
Review your auto coverage alongside renters
Coverage once you own the place you live in
Separate coverage for rising water
Protection for the people who depend on you
The full list of coverage we offer
Help when you need to file a claim
The Farnsworth Family Agency is an insurance agency, not the insurance company issuing the policy. Policies are issued by the insurer identified in the applicable quote and policy documents. Guarantees are based on the issuing insurer's claims-paying ability.
This page is general information about renters insurance, not a quote, an offer of insurance, a solicitation, or a contract. Coverage, limits, deductibles, optional coverages, rates, underwriting requirements, and availability vary by carrier and by applicant, are subject to state availability, and are governed by the terms, conditions, limitations, and exclusions of the policy actually issued. Coverage is not in force until an application is approved and a policy is delivered and in force.
A renters policy generally does not insure the building itself, does not insure your landlord's property, and generally does not cover flood. Flood coverage for personal property is purchased separately and commonly includes a waiting period before it takes effect. Every policy contains exclusions and special limits — for example on jewelry, cash, and certain categories of personal property — and those limits are stated in the policy actually issued.
Multi-policy discounts, bundling benefits, and any other discount are conditional on the carrier's rules and your eligibility, are not guaranteed, and may not be available in every situation. Nothing on this page promises a discount, a specific premium, a specific rate, or savings of any amount. Reviewing or quoting auto coverage is optional and is never a condition of obtaining renters coverage.
The Farnsworth Family Agency is a local, family-owned insurance agency in Summerville. We do not provide legal, tax, or financial advice, and we cannot guarantee approval, rates, or benefits.
Ready to cover what's yours?
Tell us a little about your rental and we'll walk you through the options — no pressure, no obligation.