Life Insurance in Summerville, SC
Protect Their Tomorrow. Start Today.
Protecting the people who count on you shouldn't feel complicated. Our Summerville team helps families across the Lowcountry compare life insurance options from multiple available carriers, so the coverage you choose fits your family, your goals, and your budget.
Get My Life Insurance Quote
A quick form. No obligation. Our team will follow up to discuss your options.
Why Life Insurance Matters
Life insurance isn't really about you. It's about the people who count on you.
Whether it's keeping up with the mortgage, replacing lost income, helping with college expenses, or simply giving your family some financial breathing room, the right coverage can make a meaningful difference.
At The Farnsworth Family Agency, we'll help you explore options that fit your family's needs, your goals, and your budget.
Replacing income
If people rely on what you earn, the death benefit can help replace some of it while a household adjusts.
Mortgages and debts
Proceeds can go toward a mortgage, loans, or credit card balances so those obligations don't land on someone else.
Final expenses
Funeral, burial or cremation, and out-of-pocket medical costs are bills that arrive at an already difficult time.
Future obligations
Childcare, education, or ongoing care for a family member can be funded long after you're gone.
Explore Your Life Insurance Options
Two different questions get mixed together in life insurance: what kind of policy it is, and how the carrier decides whether to insure you. Keeping them separate makes the whole thing easier to follow. Here's how the pieces fit.
While your family is growing
Temporary coverage for the years your household carries the most responsibility.
Term Life Insurance
Coverage for a set period — commonly 10, 15, 20, or 30 years — for the years your family leans on your income most. It pays a death benefit only if you die while the policy is in force.
Usually the lowest cost for a large death benefit, and there's no cash value. Many term policies can be converted to permanent coverage without new medical underwriting if you use the option before the policy's deadline.
Coverage built to last
Permanent policies designed to stay in force for life, provided they're kept funded as written.
Whole Life Insurance
Permanent coverage with a premium, a death benefit, and guaranteed cash value that are set when the policy is issued — costs that don't change.
Cash value grows on a guaranteed schedule that's slow in the early years. Borrowing or withdrawing reduces it, any unpaid loan reduces the death benefit, surrender charges may apply, and surrendering can have tax consequences.
Universal Life Insurance
Permanent coverage with room to adjust the premium and, within limits, the death benefit as life changes.
Cash value earns a rate the carrier declares, with a guaranteed minimum stated in the policy, and monthly charges are deducted from it. If premiums run too low or charges rise, the cash value can run out and the policy can lapse. Non-guaranteed elements can change over time.
Indexed Universal Life (IUL)
A universal life policy whose cash value crediting follows a market index, subject to a cap or participation rate and a floor that is usually 0%. You don't invest in the market, own the index, or receive index dividends.
A 0% floor doesn't mean the policy can't lose value: cost of insurance and other charges are still deducted. Caps and participation rates can change within the policy's limits, loans accrue interest, and an underfunded policy can lapse. Illustration figures are hypothetical, not a forecast. An IUL is life insurance with a death benefit, not an investment or a retirement account.
Simpler access and final expenses
Smaller policies focused on end-of-life costs. Guaranteed issue describes how a policy is issued, not a separate type of policy.
Final Expense Insurance
A small permanent policy built around funeral, burial or cremation costs and the other bills that arrive at the end of life.
Face amounts are modest compared with income-replacement coverage, so the cost per dollar of coverage is generally higher. It isn't meant to replace your income or pay off a mortgage.
Guaranteed Issue Life Insurance
Coverage for people who may be turned down elsewhere. Many guaranteed issue products ask no medical exam and no health questions.
Eligibility is set by each carrier — commonly age and state availability — and some products still ask a short eligibility question or two. Expect smaller face amounts, a higher cost per dollar of coverage, and often a graded death benefit: if death occurs during an initial waiting period, beneficiaries may receive premiums paid, sometimes with interest, rather than the full face amount. Simplified issue is different: it asks a short health questionnaire with no exam, the application is still underwritten, and the carrier can decline or rate you.
Three different paths to approval
How much health information a carrier asks for isn't the same as what kind of policy you're buying. The same term or whole life policy can be sold through more than one underwriting path.
Fully underwritten
The carrier reviews your application along with medical records, prescription history, and often a paramedical exam. It takes longer, and healthy applicants often see the most favorable pricing at this level.
Simplified issue
A short health questionnaire, no medical exam — but the application is still reviewed and underwritten. The carrier can decline you, rate you, or issue coverage at a different price than a fully underwritten policy would have been.
Guaranteed issue
Accepted without a medical exam or health questionnaire. Eligibility requirements still vary by carrier, so not every applicant qualifies for every product. It costs more per dollar of coverage and often includes a graded death benefit during an initial waiting period.
Guaranteed issue and simplified issue are not the same thing. Simplified issue still asks health questions and can be declined. Guaranteed issue is generally available without a medical exam or health questionnaire, costs more per dollar of coverage, and may pay a reduced benefit if death occurs during an early waiting period. Eligibility still differs by carrier, and availability, features, riders, and underwriting requirements vary by carrier and by applicant.
Why Choose The Farnsworth Family Agency
The Farnsworth Family Agency is a locally owned Allstate agency based in Summerville, South Carolina. We also help customers explore life insurance options from multiple available carriers, with coverage issued by the insurer identified in the policy.
Life insurance decisions usually get made with a spouse, a parent, or a grown child in the room. They go better when someone local can sit down and walk through them with you.
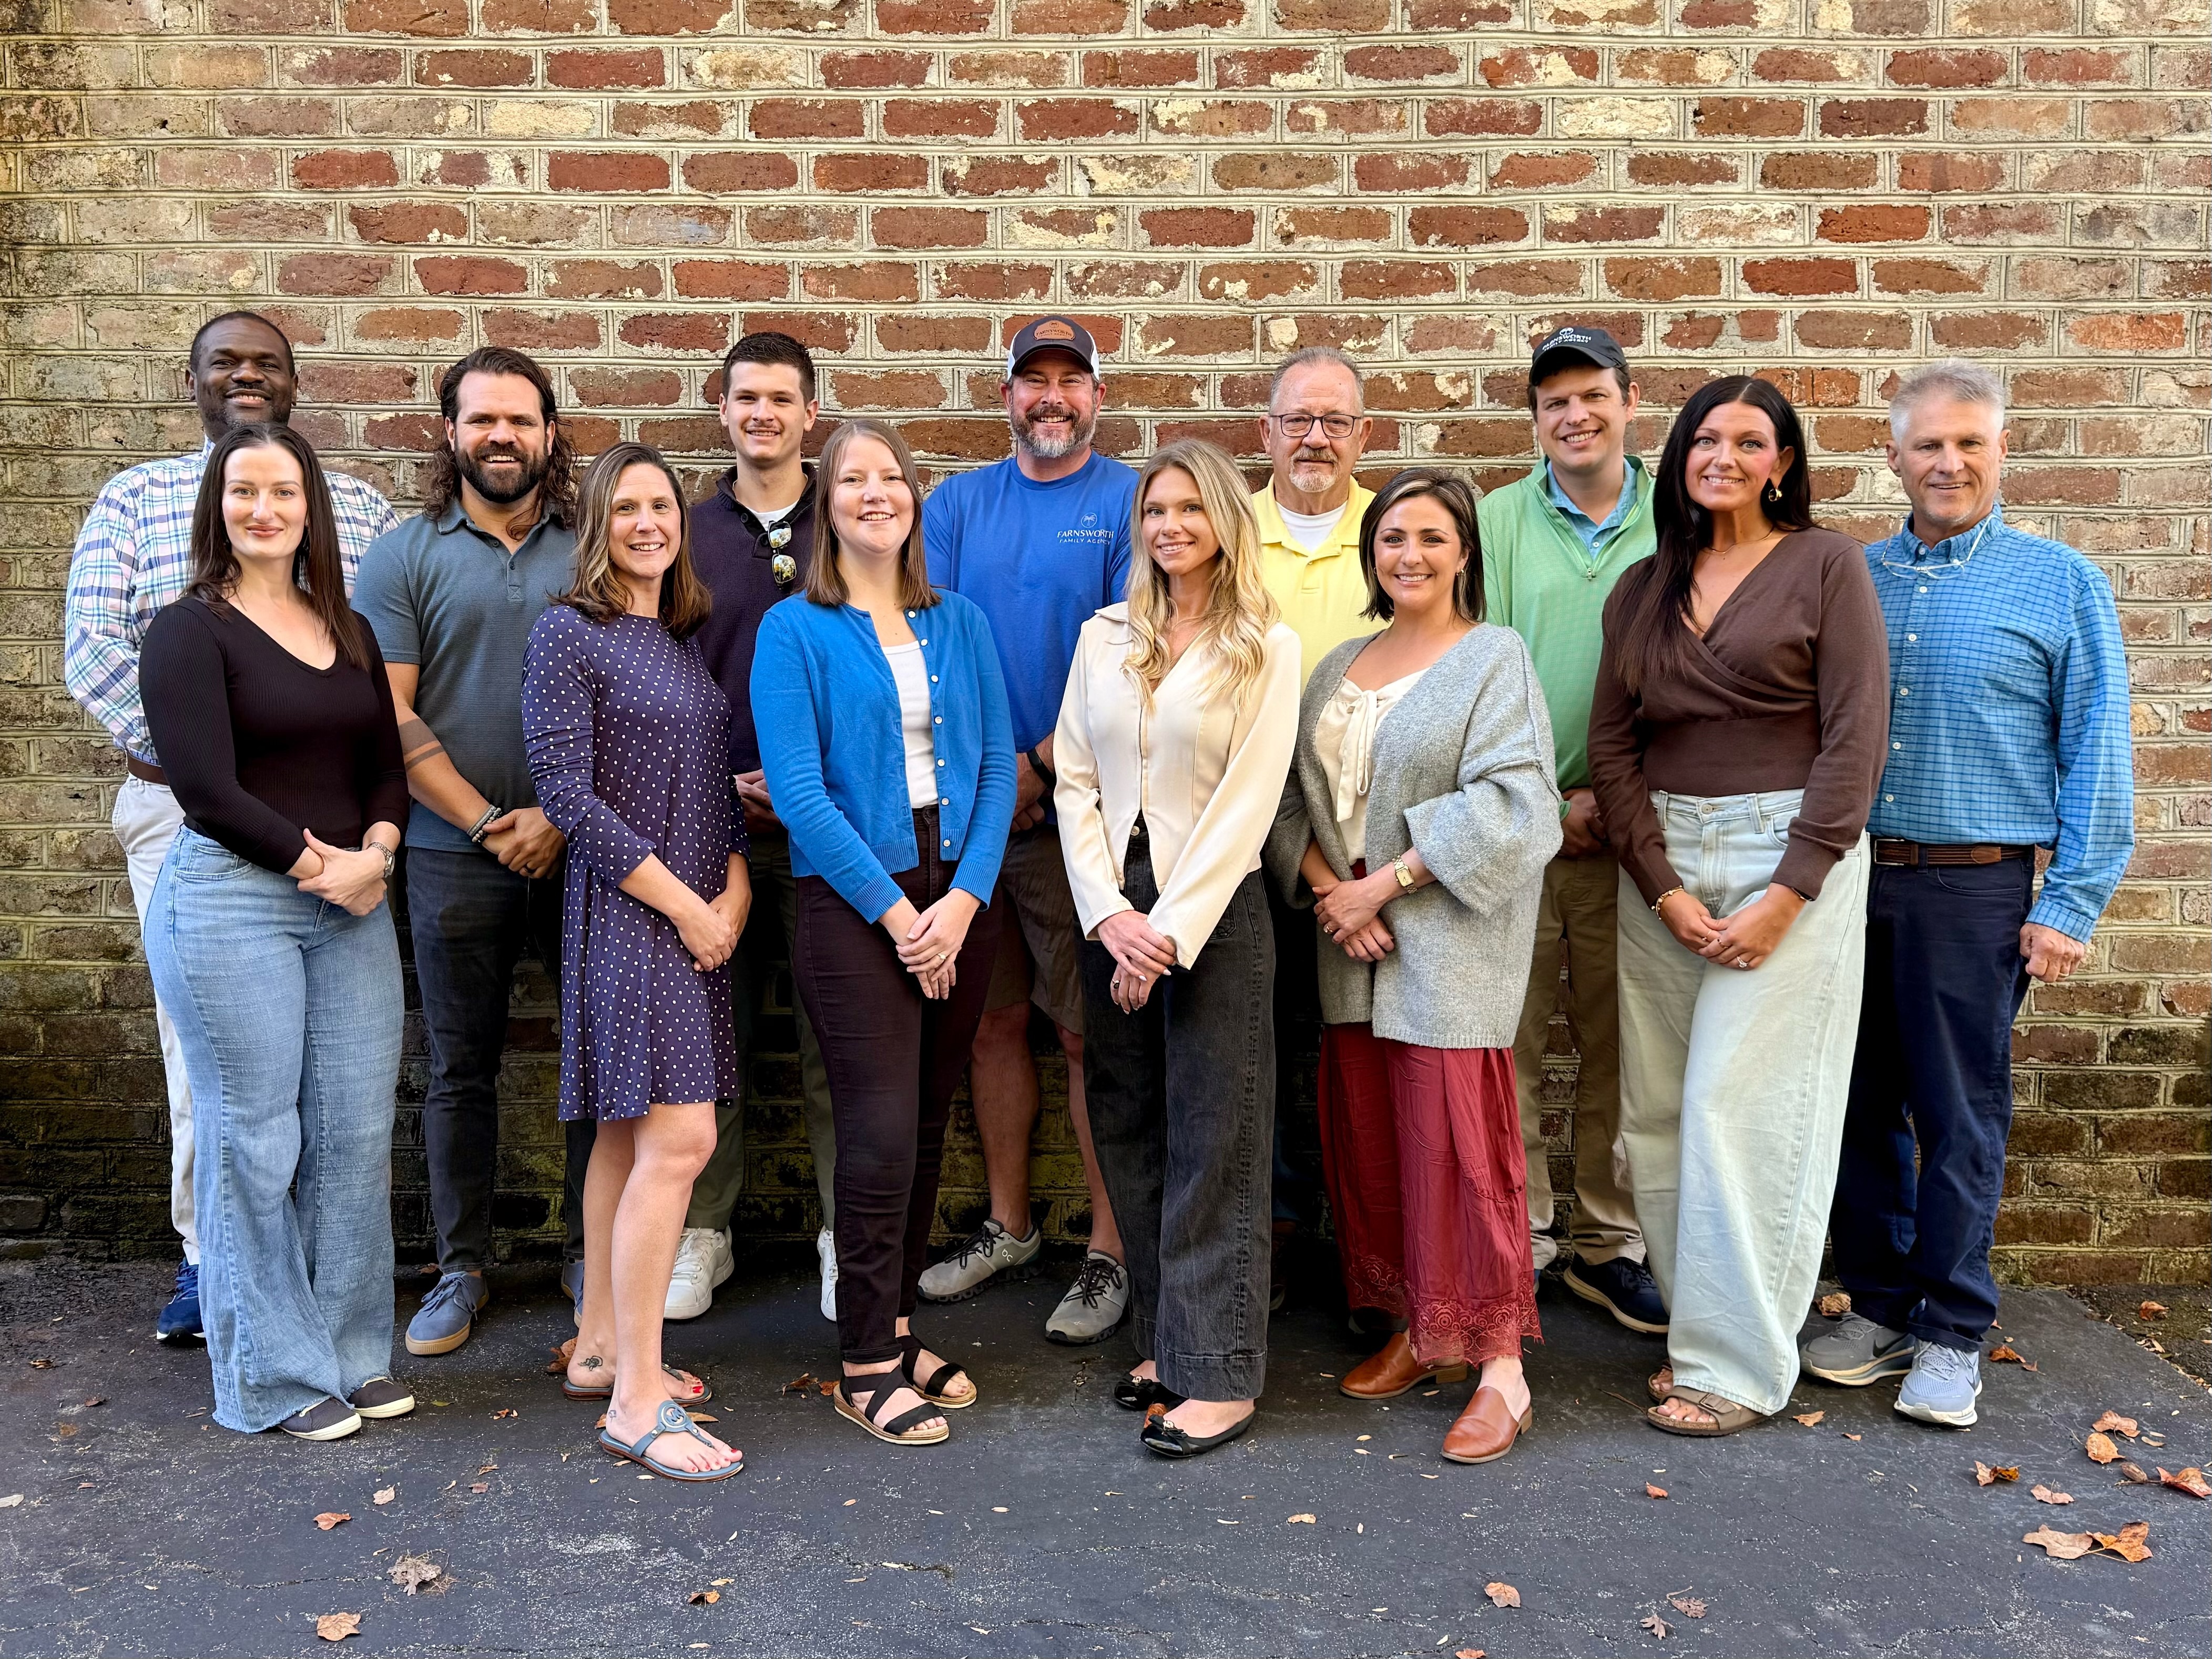
Locally owned and family-operated
Our office is at 421 Old Trolley Road in Summerville, so you can stop in, call, or sit down with our team in person.
More than one carrier to compare
We have access to multiple available life insurance carriers and product options. That means the conversation can start with your situation instead of whatever a single company happens to sell.
Plain-language conversations
We explain what a policy does, what it costs, and what it doesn't do. If a product isn't right for you, we'll say so — including when the answer is that you need less coverage than you thought.
Real people, for the long run
You work with the same team across the years, so a new child, a new mortgage, or a change in health doesn't mean starting over with a stranger.
How Much Life Insurance Do You Need?
There's no universal number, and anyone who hands you one before asking about your household is guessing. What a family actually needs comes out of five conversations.
Income
How much of your income does your household depend on, and for how many years would it need replacing?
Debts and obligations
A mortgage, car loans, student loans, credit cards, and any final expenses you don't want to leave behind.
Dependents
Children, a spouse, or a family member who relies on your income or care — and how long that support is needed.
Coverage you already have
Group coverage through an employer, an existing individual policy, savings, and any benefits already in place.
Long-term goals
Education funds, paying off a home, keeping a business running, or leaving something behind for the next generation.
Working through that list usually produces a range rather than a precise figure, and the range is the useful part. Online calculators can be a reasonable starting point, but they don't know what coverage you already carry and they assume things about your household that may not be true. Treat any number as an estimate, not a recommendation, and make the decision with the actual policy terms in front of you. We're happy to work through yours.
A Simple Four-Step Process
The form on this page is quick, and there's no obligation. Here's what happens after that.
- 1
Tell us a little about yourself
Fill out the short form on this page or call the office. Name, phone number, and roughly what you're looking for — that's enough to start.
- 2
We discuss your family's needs and goals
A conversation, not a sales pitch: who depends on your income, what you owe, what you already have in place, and what you want a policy to do.
- 3
We review available coverage options
We look at the options available to us from the carriers we're appointed with and explain how they differ — the coverage, the underwriting path, and the cost.
- 4
You decide whether to move forward
If it makes sense, we help you complete an application. If it doesn't, that's a fine outcome too. There's no cost for the conversation and no obligation to apply.
An inquiry is not an application. Nothing is submitted to a carrier until you decide to apply, and applying is not the same as being approved. The carrier underwrites each application and makes the final decision on coverage, rate, and terms — which means approval and pricing can't be promised in advance.
Life Insurance FAQs
Straight answers to what families in Summerville ask us most.
How much does life insurance cost in South Carolina?
Premiums aren't set by the state — each carrier prices coverage using its own rates and underwriting. What you pay generally depends on the type and amount of coverage, your age when the policy starts, your health and family health history, tobacco use, and the underwriting path. For the same death benefit, term coverage typically costs less than permanent coverage because it lasts a set number of years, and guaranteed issue policies usually cost more per dollar of coverage. We won't quote a figure before we know your details, and any number we give you comes from a carrier's actual rates.
What's the difference between term and whole life insurance?
Term covers a set period — commonly 10, 15, 20, or 30 years — and pays only if you die while it's in force. It generally has no cash value and is usually the least expensive way to buy a large death benefit for a limited time. Whole life is permanent: it's designed to stay in force for your lifetime as long as premiums are paid, with premiums and guaranteed values set when the policy is issued. It builds cash value you can borrow against, and borrowing reduces the cash value while any unpaid loan reduces the death benefit. Which fits depends on how long you need coverage and what you want the policy to do.
Can I get life insurance without a medical exam?
Often, yes. Simplified issue uses a short health questionnaire with no exam, though the application is still underwritten and the carrier can decline or rate you. Guaranteed issue is generally available without a medical exam or health questionnaire, with eligibility set by the carrier — commonly age, state availability, and other non-medical requirements. Fully underwritten policies may involve a paramedical exam, medical records, or a prescription check, and often offer the most favorable pricing to healthy applicants. No-exam doesn't automatically mean easier or cheaper — it's a trade-off between convenience and cost.
Are there situations where a life insurance policy won't pay?
Yes, and they're written into the contract. Two are common. A contestability period, commonly the first two years, lets the carrier review the application if you die during that window, and a claim can be affected if something material was misstated or left out. A suicide exclusion also generally applies during the first two years, in which case the carrier typically returns premiums paid rather than paying the death benefit. Beyond those, specific exclusions are listed in each policy and vary by product and carrier, so read the contract you're issued. None of this is a reason to avoid coverage. It's the reason applications should be answered accurately.
How much life insurance might my family need?
There's no single right number, and we won't hand you a formula and call it personalized advice. The usual starting points are how much income you'd want replaced and for how long, your mortgage and other debts, education or childcare you plan to fund, final expenses, and what your household already has in savings, group coverage, and existing policies. What's left over is the gap worth insuring. Some households need enough to replace income for 10 to 20 years; others mainly want to clear a mortgage and cover final costs.
Can I have more than one life insurance policy?
Yes. People commonly hold a group policy through an employer alongside an individual policy, or a term policy for income replacement while children are young plus a permanent policy for final expenses. Multiple policies mean multiple premiums and separate terms. If you're applying, carriers generally ask about existing coverage, and total coverage can be limited during underwriting. We'll look at what you already have before adding anything.
What is final expense insurance?
A small permanent policy intended to cover funeral, burial or cremation costs and other expenses that arrive at the end of life. Face amounts are modest compared with income-replacement coverage, so the cost per dollar of coverage is generally higher. Many final expense policies are written with simplified or guaranteed issue underwriting, which is what makes them available to people with health conditions. It's a focused policy — it isn't meant to replace a mortgage or your income.
What is indexed universal life insurance?
Indexed universal life (IUL) is a permanent policy whose cash value earns interest based on movement of a market index, subject to a cap or participation rate and a floor — usually 0%. It doesn't invest in the stock market directly, and you don't own the index or receive its dividends. Index credits are one part of a policy that also deducts cost of insurance and other charges every month. Caps and participation rates can change within the policy's limits, policy loans accrue interest, and a policy that isn't funded adequately can lapse. Illustration figures are hypothetical, not a promise of results. An IUL is a life insurance policy with a death benefit, not an investment or a retirement account.
Can I change my life insurance coverage later?
Usually there's some flexibility, within limits. Many term policies include a conversion option that lets you move to a permanent policy without new medical underwriting if you exercise it before the deadline. You can often add available riders, change beneficiaries, or buy an additional policy. Increasing a death benefit or changing a permanent policy's structure generally requires carrier approval and may involve new underwriting, and any change can affect cost and cash value.
Why work with a local life insurance agency?
Because the details matter, and someone has to explain them. A local agency can sit down with you, ask about your family and finances, compare options from the carriers it's appointed with, and explain what happens at claim time. We're based on Old Trolley Road in Summerville and available by phone, text, or in the office. When something changes — a new child, a new mortgage, a change in health — you talk to the same team rather than starting over with a new voice.
What happens after I request a quote?
Your inquiry goes to our Summerville team, and someone contacts you by phone, text, or email — whichever you prefer. We'll learn a little about your family and goals, then review the coverage options available to us. Nothing is submitted to a carrier until you decide to apply. An inquiry isn't an application, and neither one guarantees a policy: the carrier underwrites every application and makes the final decision on coverage, rate, and terms.
Other coverage our Summerville team handles
The full list of coverage we offer
Protect the house your family lives in
Coverage for the drivers in your household
Coverage for a business you've built
Separate coverage for rising water
Help when you need to file a claim
The Farnsworth Family Agency is an insurance agency, not the insurance company issuing the policy. Policies are issued by the insurer identified in the applicable quote and policy documents. Guarantees are based on the issuing insurer's claims-paying ability.
This page is general information about life insurance products, not a quote, an offer of insurance, a solicitation, or a contract. All products, features, riders, rates, underwriting requirements, and availability vary by carrier and by applicant, are subject to state availability, and are governed by the terms, conditions, limitations, and exclusions of the policy actually issued. Coverage is not in force until an application is approved and a policy is delivered and in force.
Every life insurance policy contains terms, conditions, limitations, and exclusions that determine whether and how a claim is paid. Many policies include a contestability period, commonly the first two years, during which the carrier may review the application, and a suicide exclusion that generally applies during an initial period. Product-specific exclusions vary and are stated in the policy actually issued.
Cash value in a permanent policy is not a bank account or an investment, is not FDIC insured, and is not guaranteed unless the policy specifically guarantees it. Policy loans accrue interest and reduce cash value and the death benefit, and may cause a policy to lapse if not repaid. Tax treatment depends on individual circumstances and can change; nothing here is tax or legal advice — please consult your own tax or legal professional.
The Farnsworth Family Agency is a local, family-owned insurance agency in Summerville. We do not provide medical, legal, tax, or investment advice, and we cannot guarantee approval, rates, or benefits.
Let's look at your family's coverage together.
Request a personalized life insurance review from our Summerville team. We'll talk through what you're protecting, compare the options available to us, and answer your questions — no pressure, no obligation to apply.